Our Location:
No. 99, Jiazi Road, Chengdu
 authorChris Lee
Yes, you can pay in China without a Chinese bank account. Foreign tourists can link supported Visa, Mastercard and other international cards to Alipay or WeChat Pay, use physical cards at participating businesses, and pay with RMB cash.
But China is not a place where one payment method works everywhere. A credit card accepted at your hotel may fail at a small restaurant, and a working mobile wallet may reject a particular QR code.
The safest approach is simple: set up a mobile wallet before arrival, bring a backup card, and carry some RMB cash for unexpected problems.
For most international tourists, Alipay or WeChat Pay is the most convenient way to handle everyday purchases in China. You do not normally need a mainland Chinese bank account to use their supported foreign-card payment features.
However, no single app or card guarantees universal acceptance.
| Payment Method | Best For | What to Watch Out For |
|---|---|---|
| Alipay | Restaurants, shops, ride-hailing and some transport services | Foreign-card authorization and merchant compatibility |
| WeChat Pay | Everyday QR purchases and WeChat-based services | Some functions do not support overseas cards |
| Visa or Mastercard | Hotels, shopping malls and larger retailers | Smaller merchants may not accept international cards |
| RMB cash | Small purchases and payment emergencies | Online bookings may require electronic payment |
| TenPayGo | An additional visitor-oriented QR-payment option | Eligibility and available features vary |
| Digital yuan (e-CNY) | Alternative digital payments where supported | Wallet setup and merchant acceptance vary |
TripChina recommendation: Prepare one working mobile wallet, a second payment option, a physical international card and a small reserve of RMB cash.
You do not need to install every Chinese payment app before your trip.
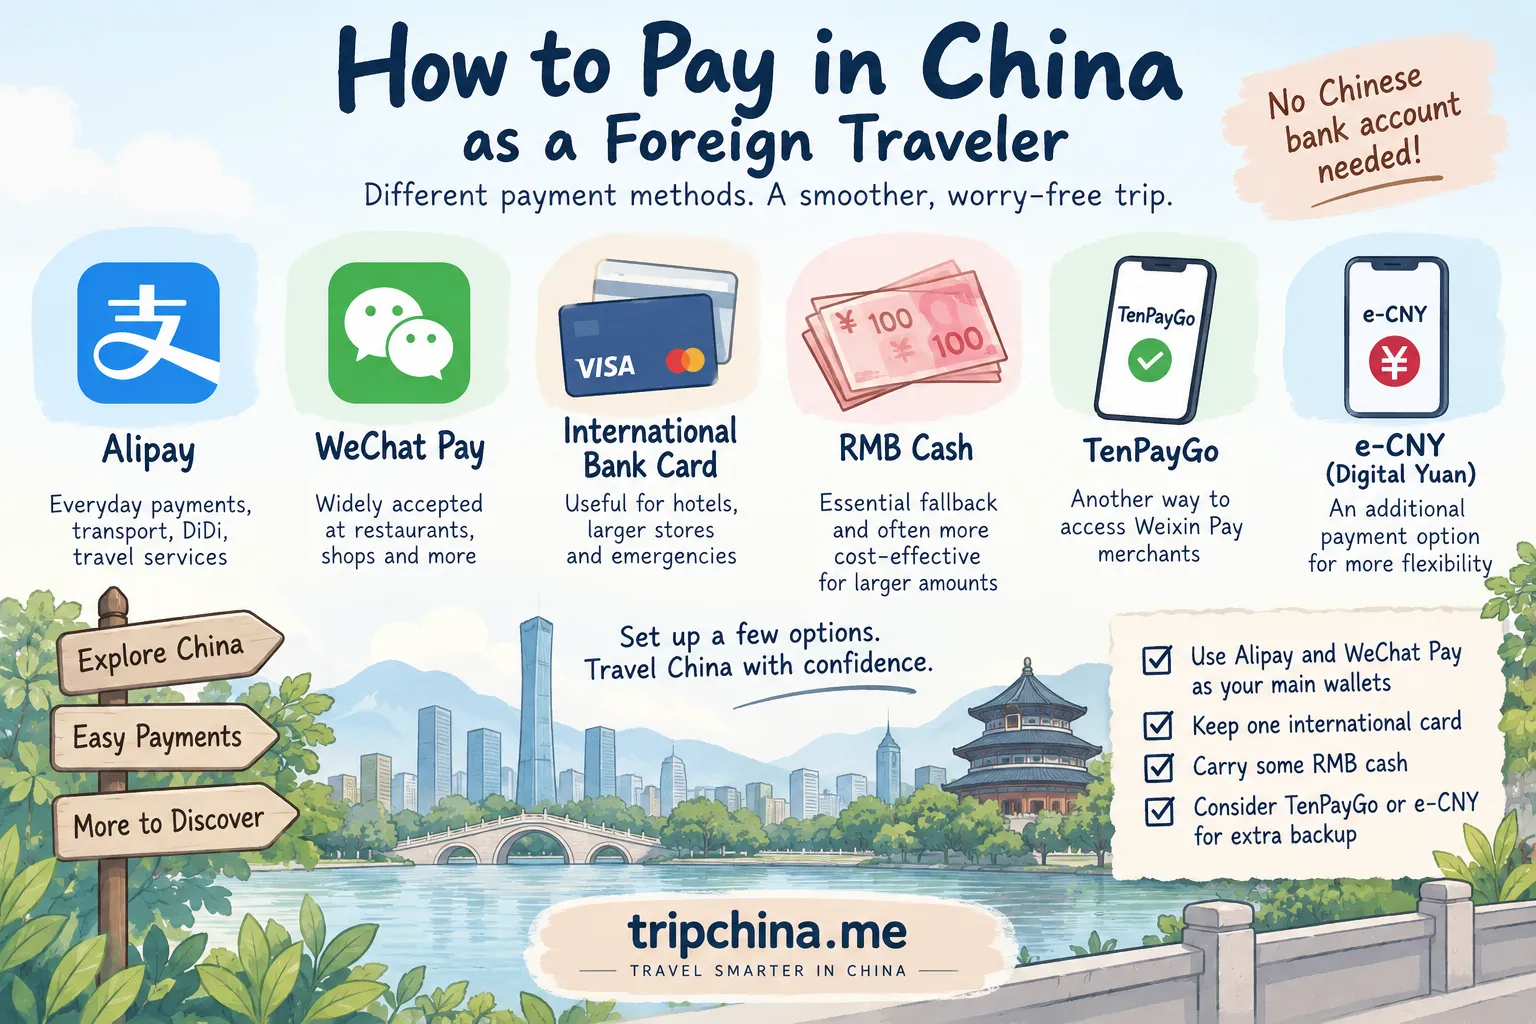
The best China payment method depends on what you are buying, whether the merchant supports your card, and how much the transaction costs.
Use this decision process when choosing between Alipay, WeChat Pay, foreign cards and cash.
For foreign-card-funded mobile-wallet transactions above RMB 200, check whether a service fee applies.
Compare the displayed wallet fee, your card issuer's foreign-transaction fee and the total cost of paying directly with an accepted international card.
A lower wallet fee does not always mean a lower total cost.
Do not repeatedly submit the same failed transaction.
Check your banking app for a declined-payment alert, then try another accepted wallet or card.
If both wallets use the same blocked bank card, switching apps may not solve the problem.
For an eligible in-person purchase, RMB cash may provide a simpler backup.
A practical payment setup includes:
The key rule: Do not depend on a single phone, payment platform or card issuer for your entire China trip.
A few preparations can prevent payment problems during your first hours in the country.
A successful card connection does not guarantee that every later transaction will be approved. Individual payments remain subject to merchant acceptance, platform rules and your issuing bank.
If your banking app allows you to manage international transactions, review those settings before departure.
Also check how your bank will deliver security verification requests while you are overseas.
China's payment system is built around mobile QR codes, but international cards and cash remain important.
The best choice depends on the merchant, the transaction type and your account's eligibility.
Alipay is one of the easiest payment options to prepare before your first trip to China.
It supports everyday QR purchases at many restaurants, shops and other participating businesses. Depending on your account and location, it can also help with transport, ride-hailing and travel services.
Foreign tourists can register using eligible overseas phone numbers and link supported international bank cards.
You generally do not need to open a Chinese bank account.
For an ordinary merchant payment, the process is usually straightforward:
Not all QR codes support the same funding sources. A merchant collection code and a personal transfer code may behave differently when using an overseas card.
If a code fails, ask whether the shop accepts another merchant payment method.
For registration screenshots, passport verification and card-binding steps, follow TripChina's step-by-step Alipay setup guide for foreigners without a Chinese bank account.
WeChat Pay is another major mobile payment option for foreign tourists.
It is particularly useful if you already use WeChat for communication or need access to a restaurant, attraction or travel service operating through a WeChat mini-program.
Like Alipay, WeChat Pay supports eligible overseas bank cards for merchant payments.
However, a linked foreign card does not necessarily unlock every feature of a domestic WeChat Pay account.
Restrictions may apply to personal transfers, red packets, wallet balance top-ups and particular mini-program transactions.
For everyday shopping, the most practical choice is often whichever wallet has already been verified and works with the merchant.
Should you install both Alipay and WeChat Pay?
For a longer China trip, having both is useful. If one platform or merchant QR code does not work, the other may provide an alternative.
But if both wallets use the same card, a bank-level decline can affect both.
For supported cards, current fees and account-specific limitations, consult TripChina's WeChat Pay setup guide for international visitors before arriving in China.
Yes. Foreign-issued Visa, Mastercard and other supported international cards can be used at participating businesses in China.
However, acceptance depends on the merchant and payment terminal.
International bank cards are particularly useful for:
Do not assume that a neighborhood café, street-food stall or small shop accepts your physical international credit card just because an international hotel does.
At checkout, look for the relevant card-network logo or ask the merchant.
A card terminal does not guarantee Visa or Mastercard acceptance. Some terminals support China UnionPay but not your international card network.
If your bank offers a choice of cards, carrying a second card provides additional protection against declines or temporary restrictions.
Apple Pay and Google Pay can also work where the merchant's terminal, card network and wallet arrangement support them. They should not be treated as universal substitutes for Alipay or WeChat Pay QR payments.
If you are traveling from the United States, your Visa, Mastercard or another eligible card may work in China, but it is not automatically accepted for every payment.
Before departure, check five things.
1. International card acceptance
US-issued cards are particularly useful at participating hotels, airports, shopping malls, larger retailers and some travel services.
Small restaurants, street stalls and neighborhood shops may rely primarily on mobile QR payments or cash.
Ask about your specific card network rather than assuming all foreign credit cards are accepted.
2. Card linking versus direct card payment
Linking a US credit card to Alipay or WeChat Pay is different from presenting the physical card at a payment terminal.
With direct card payment, the merchant processes the transaction through a supported card network.
With a Chinese mobile wallet, the platform initiates the merchant payment and requests authorization through the linked card's supported funding arrangement.
A card accepted at a hotel terminal may still fail for a particular mobile-wallet payment, and vice versa.
3. Foreign-transaction fees
Some US credit cards charge a foreign-transaction fee, often around 3%, while other cards waive it.
This is separate from any mobile-wallet service fee.
Check your issuer's terms before paying for an expensive purchase.
For example, if a RMB 1,000 wallet payment attracts a 3% service fee, that adds RMB 30 before any applicable issuer charges.
Do not assume the bank fee and wallet fee are mutually exclusive.
4. ATM currency conversion
When withdrawing RMB from a Chinese ATM, you may be offered the choice of accepting a conversion into US dollars or proceeding in RMB.
The dollar conversion is commonly called dynamic currency conversion, or DCC.
Choosing RMB generally avoids the ATM provider's own currency-conversion offer, although your bank may still charge withdrawal or exchange fees.
A debit card is usually worth considering for ordinary cash withdrawals because credit-card cash advances can involve additional fees and interest.
5. Bank authentication and declined payments
Check whether your bank requires you to enable international transactions or submit a travel notice. Many issuers no longer require advance notification, but account settings and security policies vary.
Make sure you can receive verification through your banking app or another supported authentication method while abroad.
If a transaction is declined, review issuer alerts before assuming the merchant or payment app is at fault.
Practical setup for US travelers: Use one eligible card with Alipay or WeChat Pay, keep a separate physical card from another issuer, and carry RMB cash for immediate backup.
Yes. RMB cash remains a valid payment method in China and an important backup for international visitors.
It is particularly useful when:
China has introduced measures to maintain and improve cash acceptance, including services designed to help overseas visitors obtain smaller RMB notes.
However, cash does not solve every payment problem.
Certain online reservations, app-based services and unattended payment systems may require electronic payment or an alternative purchasing channel.
Carry smaller denominations where possible. A large banknote may be inconvenient for a low-cost purchase if the merchant has limited change.
Best approach: Use mobile payments for convenience, but do not treat cash as obsolete.
Payment acceptance varies by merchant, location, card network and the rules of the payment platform.
The comparison below reflects common payment arrangements and published guidance. It is not a record of live field tests or a guarantee of acceptance at individual businesses.
| Travel Scenario | Recommended First Option | Possible Problem | Practical Backup |
|---|---|---|---|
| Street food and small noodle shops | Alipay or WeChat Pay | Personal QR codes may not support foreign-card-funded payments | RMB cash |
| Cafés and convenience stores | Mobile-wallet merchant QR payment | Some merchant configurations or cards may be unsupported | Second wallet or cash |
| Shopping malls and larger retailers | Accepted international card or mobile wallet | The terminal may not support your card network | Another card or wallet |
| Hotel front desk | Prepaid booking or confirmed international card | Deposits may require separate authorization | Another accepted payment method |
| DiDi ride | Verified in-app payment | Card authorization may fail | Another supported ride service |
| Subway and city buses | City-supported transit payment or ticket | Foreign-card transit eligibility varies | Single-journey ticket |
| Train tickets | 12306 or a compatible booking platform | Identity verification or payment-channel restrictions | Alternative booking channel |
| Attraction tickets | Official ticketing service or supported platform | Booking or payment requirements vary | Alternative authorized ticket channel |
| Larger purchases | Compare direct card and mobile wallet | Additional fees, holds or refund conditions | Another accepted method |
A payment method working in one Chinese city does not guarantee identical acceptance elsewhere.
Likewise, a successful transaction at one merchant does not prove that the same foreign card will work with every QR code.
Use the following sections to prepare for the travel expenses most likely to cause problems.
Many local restaurants and cafés use QR-code payments.
You may scan the merchant's code or present your own payment code.
For small everyday purchases, Alipay or WeChat Pay is usually more convenient than searching for a card terminal.
A personal collection QR code and a registered merchant payment code may support different transaction types.
If your overseas card cannot fund a particular QR payment, ask whether the business has another supported merchant code.
If not, try your second wallet or offer RMB cash.
Do not repeatedly scan the same code if the transaction is being rejected.
Hotels can present additional payment challenges because room charges and security deposits may be processed separately.
Before arrival, confirm whether:
A hotel accepting a reservation through an international booking website does not automatically mean its reception desk accepts every overseas card.
For independent accommodation bookings, TripChina's China hotel booking guide for foreign passport holders explains how to check international guest acceptance, payment conditions and potential check-in problems before confirming a reservation.
DiDi and other participating ride-hailing services can offer a convenient way to travel around Chinese cities.
Foreign visitors may be able to book through the DiDi app or supported ride-hailing services inside Alipay or WeChat.
Before requesting a vehicle, make sure your selected payment method is working.
A payment card stored in a ride-hailing account is not necessarily accepted for every journey or transaction.
Switching from one app to another will not always fix a decline if the same issuing bank is blocking the underlying payment.
If you are unsure whether you need a Chinese phone number or how to configure your payment method, TripChina's guide to using DiDi in China without a Chinese phone number explains account setup, booking, pickup locations and common payment problems.
Mobile payments are widely used for public transportation, but there is no single nationwide fare-payment system.
Depending on the city, travelers may be able to use a transit QR code, supported contactless card, local transport pass or single-journey ticket.
Beijing, for example, supports eligible foreign-issued cards for direct tap-to-ride payments on participating rail services.
Other cities may have different arrangements.
A shopping wallet that works at restaurants may not automatically qualify for a city's transit QR code.
If a transit QR function cannot be activated with your overseas card, buying a station ticket may be simpler than troubleshooting the app at the fare gate.
Check local operator rules before traveling, particularly when relying on contactless international cards.
For travel reservations, payment acceptance is only one part of the process.
You may also need a booking platform that accepts your passport information and completes the required identity verification.
China Railway's official 12306 service and international booking platforms offer different workflows for foreign visitors.
For example, some travelers may prefer to use their existing Chinese mobile wallet, while others may find an international booking platform's card checkout easier.
Before selecting a booking channel, compare:
TripChina's 12306 vs Trip.com train ticket booking comparison for foreigners explains the differences and helps international travelers choose a suitable booking method.
For attraction tickets, use official or authorized booking channels where available and verify payment methods before the reservation deadline.
Foreign-card mobile payment fees matter most when you make larger purchases.
Published general rules for overseas cards linked to major Chinese mobile wallets have commonly used the following fee structure:
| Transaction Amount | General Wallet Service-Fee Reference |
|---|---|
| RMB 200 or less | No additional wallet service fee |
| More than RMB 200 | 3% of the transaction amount |
| Eligible promotional transaction | Qualifying promotion terms apply |
These are general reference rules, not a guarantee of the fee charged to every account.
Payment providers may apply temporary promotions, service-specific terms or other eligible exemptions.
Always confirm the actual fee displayed before completing the payment.
| Purchase | Example Wallet Fee |
|---|---|
| RMB 100 | RMB 0 under the general exemption |
| RMB 400 | RMB 12 |
| RMB 1,000 | RMB 30 |
| RMB 2,000 | RMB 60 |
These examples assume the general 3% service fee applies to transactions above RMB 200.
An eligible promotion may reduce or waive the fee.
For small everyday purchases, convenience and merchant compatibility may matter more than fee differences.
For a large hotel payment, electronics purchase or shopping bill, compare the final mobile-wallet charge with direct payment using an accepted international card.
Remember that your issuing bank may charge its own foreign-transaction or currency-conversion fee.
Money-saving tip: Compare the complete payment amount rather than assuming Alipay, WeChat Pay, cash or a physical credit card is always cheapest.
Eligible international-card users may receive temporary fee waivers or other payment promotions.
The available benefit depends on the campaign period, account eligibility, card requirements and transaction limits.
Some offers may include a specified promotional period or daily qualifying spending allowance.
However, eligibility and campaign terms can change.
Do not assume a fee waiver mentioned in an older travel article is automatically available to your account.
Check the current WeChat Pay offer and the final transaction fee before making a large purchase.
Do not assume that dividing one purchase into several transactions will eliminate applicable fees.
A merchant may not permit the arrangement, and repeated payments can trigger card-issuer or payment-platform risk controls.
For legitimate larger purchases, compare accepted payment methods and choose the one with the clearest total cost.
International visitors can obtain Chinese yuan through supported ATMs, commercial bank branches and authorized currency-exchange services.
You do not need to open a Chinese bank account simply to withdraw cash from a compatible ATM with an overseas card.
Look for an ATM displaying a network compatible with your international debit or credit card.
Before confirming the withdrawal, check:
Credit-card cash advances may incur additional fees and interest. A debit card may therefore be preferable for routine cash withdrawals, depending on your bank's terms.
Some ATMs and card terminals offer to process a transaction in your home currency.
This is called dynamic currency conversion, or DCC.
For US travelers, the screen may offer USD instead of RMB.
The home-currency option uses a conversion rate provided by the ATM operator or payment service.
Choosing RMB generally avoids accepting that provider's conversion offer. Your card issuer may still apply foreign-exchange or withdrawal fees.
Compare the disclosed rates and charges before confirming.
There is no single correct amount for every China itinerary.
For a short city trip where your mobile wallets work, a modest reserve of smaller RMB banknotes may be sufficient.
For remote destinations, late-night arrivals or journeys with unreliable connectivity, consider a larger practical reserve.
Keep the amount appropriate to your itinerary and store it securely.
Cash is a backup, not a reason to carry your entire travel budget.
A failed payment does not always mean your foreign card is unsupported.
The problem may involve the merchant, payment platform, card issuer or internet connection.
Identifying the cause is usually more effective than repeating the transaction.
| Payment Problem | Possible Cause | What to Try |
|---|---|---|
| Cannot link an overseas card | Identity or issuer authorization requirements | Check verification and contact your bank |
| Card linked but payment declined | Issuer security or merchant restrictions | Review bank alerts and use another accepted method |
| One merchant QR code fails | Unsupported QR transaction type | Try another merchant code, wallet or cash |
| Both wallets fail with the same card | Possible issuer-level restriction | Try a card from another issuer |
| Payment app requests verification | Account or security control | Complete legitimate in-app verification |
| Phone has no mobile data | Connectivity problem | Use a physical payment backup |
| Hotel rejects a card | Terminal compatibility or deposit policy | Ask for an alternative accepted method |
| Phone is lost or battery is empty | Device unavailable | Use cash or physical card and secure accounts |
Repeated payment attempts may not resolve the issue and can cause additional security checks.
Determine whether the merchant, payment platform or issuing bank is responsible.
Open your banking app and look for overseas transaction alerts, authentication requests or temporary security restrictions.
If necessary, contact your issuer through an official support channel.
If Alipay fails, try WeChat Pay.
If both wallets rely on the same declined card, switch to another independently issued card or a different accepted payment route.
For eligible in-person purchases, RMB cash may resolve the immediate problem.
If your bank confirms the transaction was not blocked, use the payment provider's official customer support.
Follow legitimate verification instructions and never share passwords or one-time security codes with third parties.
Some payment functions require a working internet connection.
Before traveling, make sure your phone supports your chosen international roaming, travel eSIM or local SIM arrangement.
If you arrive without mobile data, TripChina's step-by-step guide to restoring internet access after arriving in China explains how to troubleshoot roaming, eSIM and Wi-Fi connections before attempting another online payment.
For most short-term tourists, Alipay, WeChat Pay, international cards and cash already provide a practical payment setup.
Additional wallets can be useful, but they are not essential.
TenPayGo offers an alternative payment-focused route to participating Weixin Pay merchants for eligible users.
It may appeal to visitors seeking a separate payment option rather than relying entirely on the broader WeChat app.
However, supported cards, eligibility and available functions depend on the current service arrangements.
If your existing Alipay and WeChat Pay accounts work reliably, there may be little reason to add another payment service solely for a short trip.
If you are considering another QR-payment option, TripChina's TenPayGo review for international tourists comparing its payment features and limitations examines where the service may be useful and what travelers should check before setting it up.
The digital yuan, or e-CNY, is China's central bank digital currency.
It is separate from Alipay and WeChat Pay.
Eligible overseas visitors may be able to register for the official e-CNY app using an overseas phone number and access supported funding arrangements.
Certain hardware-wallet products also offer alternative payment capabilities.
However, merchant acceptance varies, and an e-CNY wallet should not be assumed to work wherever Alipay or WeChat Pay is accepted.
For typical visitors, e-CNY is an optional alternative rather than the first payment method to set up.
Some overseas mobile wallets participate in cross-border QR-payment arrangements in mainland China.
Examples include selected wallet services from Hong Kong, Singapore, Malaysia, Thailand and other participating markets.
Whether your wallet works depends on the provider, account eligibility and merchant network.
Check the official provider's coverage before relying on it for a trip.
Some outdated travel advice can leave foreign visitors unnecessarily worried about everyday purchases.
The following misconceptions are worth correcting before departure.
Mobile payments are extremely common, particularly in major cities, but relying entirely on one phone is risky.
Cash remains useful when mobile data fails, an account is temporarily restricted or a merchant cannot process your preferred payment.
However, online-only transactions and certain unattended services may require electronic payment.
Reality: Bring a modest RMB cash backup, even if you expect to use mobile payments most of the time.
A successfully linked card does not guarantee that every merchant QR code can accept a foreign-card-funded payment.
Personal transfers, certain collection codes and restricted transaction categories may not support overseas cards.
Reality: If a QR payment fails, ask for another supported merchant payment method rather than repeatedly scanning the same code.
Some merchant terminals support domestic Chinese payment networks without accepting every international card brand.
Having a card machine does not guarantee that your overseas card will work.
Reality: Confirm the accepted network and keep a working mobile-wallet alternative.
Apple Pay and Google Pay rely on compatible contactless terminals and supported card arrangements.
They do not generally replace Chinese QR-based merchant payment services.
Reality: Set up Alipay or WeChat Pay if you want broader access to everyday mobile payments.
The e-CNY system offers an additional payment option, but it is not necessary for most short leisure trips.
Availability, setup conditions and merchant acceptance may vary.
Reality: Prioritize a working mainstream wallet, physical card and cash before considering optional alternatives.
China's established mobile payment networks offer security controls, but tourists should still protect their payment accounts and banking information.
The most useful precautions are straightforward.
Check merchant details before approving a QR payment.
Confirm the displayed merchant name and RMB amount. If a QR code appears altered or does not match the business, ask staff to verify it.
Never share verification codes or card security details.
Keep your CVV, banking passwords, one-time passwords and mobile-wallet login codes private. Do not disclose them to someone claiming to provide payment support.
Enable transaction notifications.
Banking alerts help you identify unexpected charges, blocked overseas transactions and duplicate payments more quickly.
Use authorized currency-exchange services.
Obtain RMB through banks, licensed exchange providers and supported ATMs rather than relying on unknown individuals offering informal exchange deals.
Keep payment backups independent.
Where possible, carry cards from different issuing banks. Linking several cards from the same issuer to one wallet may not provide sufficient protection against an issuer-wide restriction.
Keep records of expensive purchases.
Retain receipts and booking confirmations for accommodation, electronics, luxury goods and other large expenses.
These can help with refunds, disputes and checking unexpected charges.
If you lose your phone, secure the device, payment accounts and linked bank cards through their official security channels as soon as possible.
Different travelers may need different backup arrangements.
| Traveler | Recommended Setup | Main Consideration |
|---|---|---|
| First-time tourist | Mobile wallet, physical card and cash | Everyday convenience |
| Solo traveler | Verified wallet, independent backup card and cash | One-account failure |
| Couple or family | Separate payment options for each adult | Avoid relying on one phone |
| Short stopover | Working wallet, accepted card and cash | Minimal setup |
| Longer independent trip | Two wallets, cards from different issuers and cash | Greater resilience |
| Business traveler | Wallets and suitable physical cards | Deposits and large payments |
| Traveler with an eligible overseas e-wallet | Existing wallet plus another accepted method | Provider coverage |
The important principle is not the number of payment apps you install.
It is whether you can continue paying for meals, accommodation and transportation when one payment route stops working.
Complete these checks before traveling to China.
Do not assume that successfully linking a card proves every merchant transaction will work.
If you can only complete one payment-related preparation task before departure, prioritize setting up a supported wallet and confirming an independent backup.
Payment is also just one part of preparing your phone for China. Navigation, translation, train bookings and ride-hailing may require unfamiliar apps.
For a broader preparation checklist, see TripChina's seven essential China travel apps to install before your flight.
No. Foreign tourists can link supported overseas bank cards to Alipay or WeChat Pay, use accepted international cards at participating businesses, and pay with RMB cash. A mainland Chinese bank account is not required for these payment options.
Yes, if the merchant accepts your card network. Visa, Mastercard and other supported international cards are useful at participating hotels and larger retailers. Eligible cards can also be linked to Alipay or WeChat Pay for supported merchant payments.
Both are useful. Alipay is a practical starting point for everyday purchases and travel services, while WeChat Pay is convenient for shopping and supported mini-programs. The better choice is whichever service works with your card and the merchant.
Cash can cover many in-person purchases, but certain online reservations and app-based services may require electronic payment. Keeping a working digital option is advisable.
Not necessarily. Eligible users can register using supported overseas phone numbers, subject to account and verification requirements. Reliable internet access and a working authentication method remain important.
Possible reasons include merchant QR compatibility, issuer authorization, account security restrictions or transaction limits. Check the error message and banking alerts before trying an alternative payment method.
Published general rules commonly provide no additional wallet service fee for transactions of RMB 200 or less and a 3% fee above RMB 200. Actual charges may differ because of eligible promotions or payment-specific terms. Check the final fee in your app.
No. These services may work at supported contactless terminals, but they are not universal replacements for Chinese merchant QR payments.
Some do, depending on the ATM network and card issuer. Look for compatible network logos and review your bank's overseas withdrawal, cash-advance and currency-conversion fees.
You can arrange RMB before departure or obtain it through supported ATMs, banks and authorized exchange services after arrival. Compare costs and availability, and keep a backup plan for accessing cash.
Usually not. These are optional alternatives. For most short visits, a working Alipay or WeChat Pay account, physical international card and cash backup provide a practical starting point.
The easiest way to pay in China as a foreign tourist is to use Alipay or WeChat Pay for everyday QR purchases, an international card where accepted, and RMB cash as backup.
You do not need a Chinese bank account for these supported payment methods.
Before departure, verify at least one mobile wallet, check your international card settings and arrange reliable mobile connectivity.
For larger purchases, compare the final payment cost rather than assuming one method is always cheapest.
If a transaction fails, identify whether the problem involves the merchant, payment platform or card issuer, then switch to a working alternative.
TenPayGo and e-CNY may offer additional options, but most leisure travelers should prioritize getting their main payment setup working reliably.
The best China payment plan isn't one perfect app. It's having another way to pay when the first one doesn't work.
This guide draws on Chinese government payment guidance and TripChina's research into practical payment options for overseas visitors. The merchant scenarios are illustrative comparisons based on published rules, not live field tests. Card eligibility, fees, merchant acceptance and promotional terms may vary. Confirm current requirements with the relevant payment platform, card issuer or merchant before making a transaction.
TripChina.me creates practical China travel guides shaped by real local experience, helping independent travelers navigate transport, payments, food, neighborhoods, and the cultural details that make traveling in China easier and more meaningful. Find the guide for your destination at tripchina.me.

Comments are closed.


[…] you are figuring out how to pay booking deposits without a Chinese bank account, our guide to paying in China with Alipay, WeChat Pay, international cards, and cash walks through realistic payment options for foreign […]
The four-layer setup is exactly how I'd frame it after living through the cash-to-QR transition here. Two things I'd add from experience: first, the 3% fee above RMB 200 on foreign cards surprises most newcomers — it makes cash genuinely competitive for mid-size purchases, not just emergencies. Second, issuer risk controls are the silent killer: a card that works fine for weeks can suddenly get blocked during a travel-heavy stretch, and the decline always happens at the worst register. Calling your bank before a long domestic train trip saves real pain.
Does the guide plan to cover the Alipay mini-program workaround for DiDi? That's the piece returning visitors ask about most.
Indeed! Your experience and suggestions are excellent. I will update this guide and include information on using the Digital RMB and TenPayGo, as these two payment methods might be more convenient for most foreign tourists.